Stage 2: First Job & 20s (Ages 18–28)

From Your First Offer Letter to Financial Freedom.

36-panel interactive graphic novels following Rahul (22) and Tech Lead Priya (26). Deconstruct CTC, beat inflation, dodge credit card debt traps, and start investing from month one.

Start Chapter 1 Comic (36 Panels)➜
Rahul arriving at Bangalore Tech Campus - FinAcademy
Chapter 1: The ₹12L CTC Mystery

Your Career Financial Roadmap

Complete missions to level up your real-world money skills.

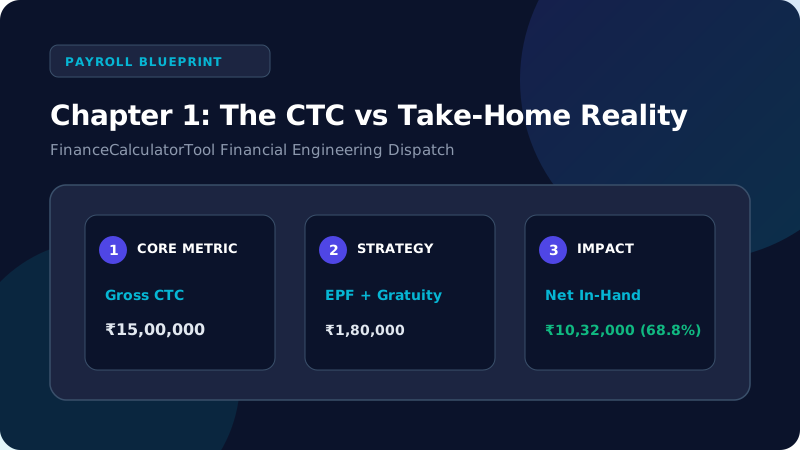
The First Offer Letter: Decoding the CTC Take-Home Illusion
CHAPTER 1 • First Job & Compensation6 min read

The First Offer Letter: Decoding the CTC Take-Home Illusion

Why an ₹8 Lakhs or ₹12 Lakhs CTC offer letter credits significantly less money to your bank account on day one. Master Basic, HRA, EPF, Gratuity, and TDS.
💡 Core Rule:Fixed In-Hand = CTC minus (Employer EPF + Employee EPF + Gratuity Accrual + TDS + Prof Tax). Never budget lifestyle expenses based on gross CTC.
The 22yo Tax Wizard: Old vs. New Tax Regime for Fresh Earners
CHAPTER 2 • Income Tax & Deductions5 min read

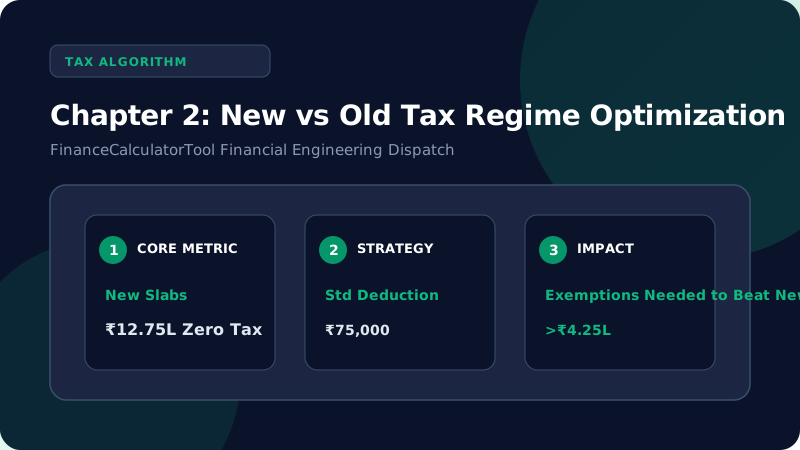
The 22yo Tax Wizard: Old vs. New Tax Regime for Fresh Earners

Why the New Tax Regime FY 2026-27 is a game-changer for salaries up to ₹12.75 Lakhs (Zero Tax!). Stop buying fake insurance for 80C deductions.
💡 Core Rule:Under FY 2026-27 Budget rules, income up to ₹12.75 Lakhs is 100% tax-free under the New Regime (₹75k Standard Deduction + ₹12L Sec 87A rebate). For 90% of freshers, New Regime is superior.
The Health Shield & 6-Month Emergency Cushion
CHAPTER 3 • Risk & Protection5 min read

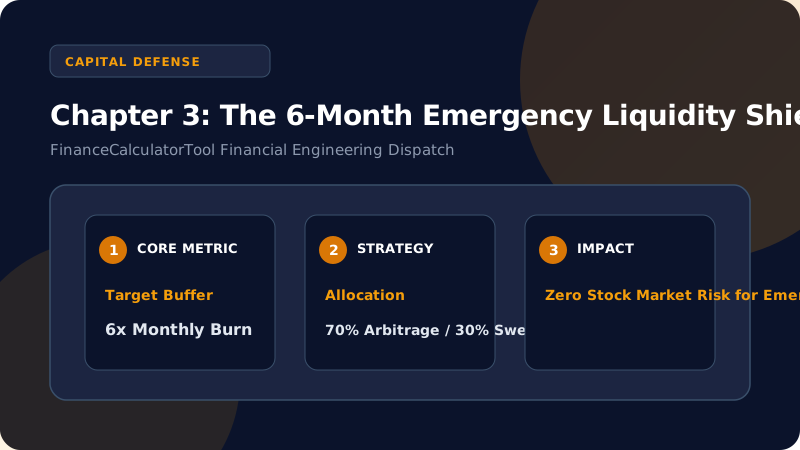
The Health Shield & 6-Month Emergency Cushion

Why relying solely on corporate health insurance is a dangerous gamble. Build a liquid 6-month survival buffer before investing a single rupee in stocks.
💡 Core Rule:Emergency Fund = 6 months of living expenses in high-yield liquid funds or bank sweep FDs. Personal Health Cover (₹10–15L) is non-negotiable outside employer group insurance.
The ULIP & Endowment Trap: Never Mix Insurance with Investment
CHAPTER 4 • Insurance & Wealth Creation6 min read

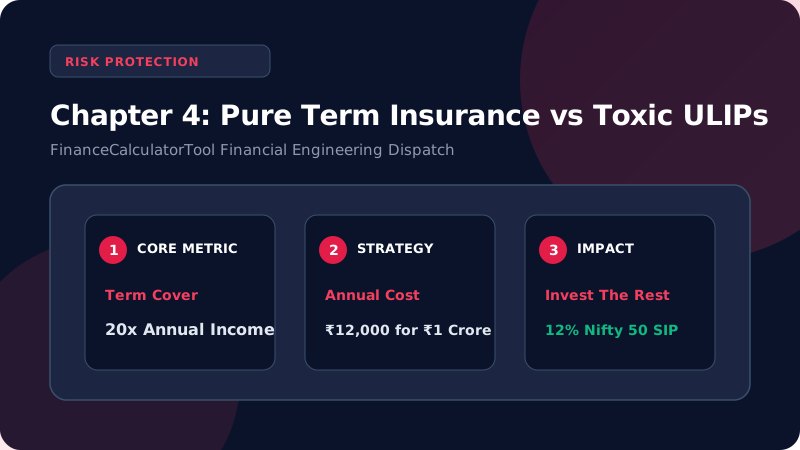
The ULIP & Endowment Trap: Never Mix Insurance with Investment

Why guaranteed insurance-cum-investment schemes yield less than 5% returns. Master the pure formula: Pure Term Plan + Direct Index Funds.

💡 Core Rule:Insurance is for risk protection. Investment is for wealth creation. Combining them creates high agent commissions, low life cover, and sub-inflation returns. Buy Pure Term Insurance; invest the difference in Direct Mutual Funds.
Credit Cards & The CIBIL Score Blueprint: The 42% APR Trap
CHAPTER 5 • Credit & Debt Management6 min read

Credit Cards & The CIBIL Score Blueprint: The 42% APR Trap

How paying only the "Minimum Due" triggers 42% annualized interest and destroys your credit score. Master the 30% utilization rule and 50-day interest-free cycle.
💡 Core Rule:Always pay the "Total Amount Due" in full before the due date. Never pay "Minimum Amount Due". Keep utilization under 30% of your limit to build an 780+ CIBIL score.
The Direct Index Fund Playbook: Why 1% Commission Destroys 30% Wealth
CHAPTER 6 • Wealth & Equity Compounding6 min read

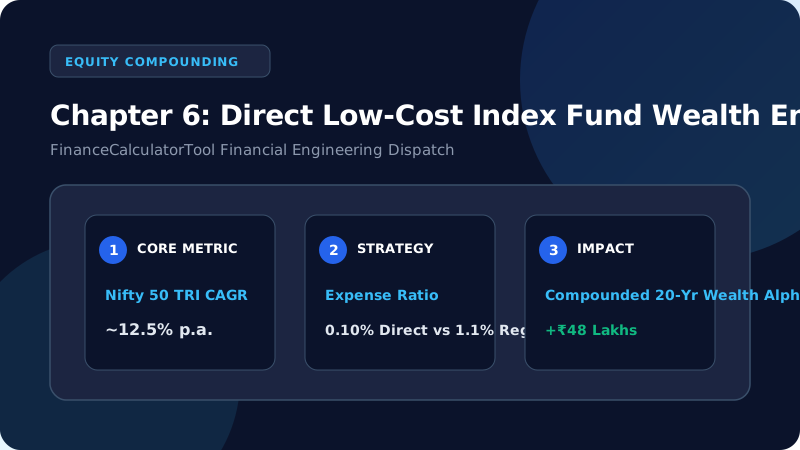
The Direct Index Fund Playbook: Why 1% Commission Destroys 30% Wealth

Why starting a ₹5,000 monthly SIP in your 20s beats investing ₹15,000 in your 30s. Master Regular vs. Direct Mutual Funds and the Nifty 50 compounding engine.
💡 Core Rule:Compounding is exponential over time ($t$). Invest in DIRECT Mutual Funds (0.1% TER) instead of Regular Plans (1.5% TER). That tiny 1.4% difference saves you ₹40–60 Lakhs in lost commissions over 25 years.
The First Car & The 20/4/10 Rule: Down Payment, EMI Trap & Total Cost of Ownership
CHAPTER 7 • Car Affordability & Debt Traps🔥 Season 27 min read

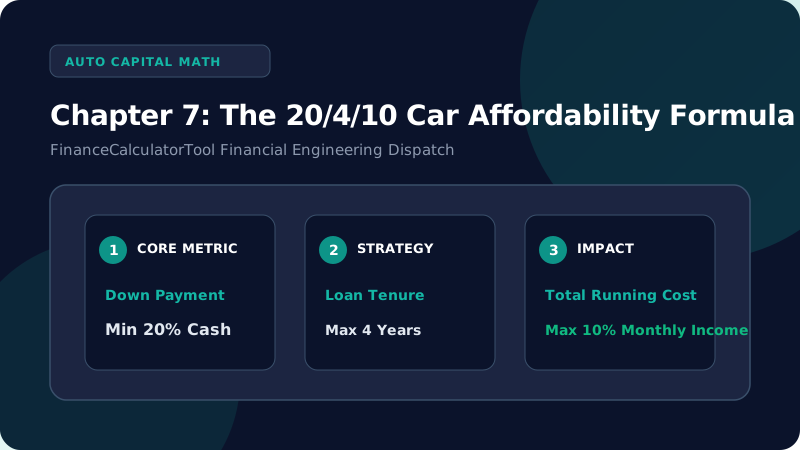
The First Car & The 20/4/10 Rule: Down Payment, EMI Trap & Total Cost of Ownership

Why buying a ₹16 Lakh SUV on a 7-year zero-downpayment loan drains over 57% of your take-home pay. Master the 20/4/10 rule and Total Cost of Ownership.

💡 Core Rule:The 20/4/10 Rule: Put down at least 20% in cash, finance for no longer than 4 years, and ensure total vehicle operational expenses (EMI, fuel, insurance, maintenance) stay strictly under 10% of monthly take-home pay.
Freelance, Moonlighting & Section 44ADA: The 50% Presumptive Tax Blueprint
CHAPTER 8 • Freelance & Presumptive Tax🔥 Season 27 min read

Freelance, Moonlighting & Section 44ADA: The 50% Presumptive Tax Blueprint

How software engineers and consultants legally claim 50% tax-free expenses under Section 44ADA with zero CA audits and a single March 15 advance tax payment.

💡 Core Rule:Section 44ADA allows specified professionals with gross receipts up to ₹75 Lakhs (digital receipts ≥95%) to declare a flat 50% as taxable profit, exempting them from bookkeeping and audits, with 100% advance tax payable in a single installment by March 15.
Authoritative Standards & Citations

FinAcademy curriculum strictly adheres to Indian Income Tax rules (Finance Act 2024 / FY 2026-27), Employee Provident Fund Organization (EPFO), Code on Social Security, 2020 (formerly the Payment of Gratuity Act, 1972), and SEBI Direct Mutual Fund regulations.