Part 1: Bank Relationship Manager & The "Guaranteed Return" Pitch
Panels 1 to 18 • Bangalore Tech Corridor Investigation
"Mr. Rahul! Welcome to Apex Premier! Fresh Associate Software Engineer at Nexa Tech, right? We hold tremendous respect for young tech achievers like you. Skip the counter line—come relax in my private cabin over a fresh espresso!"
"Rahul, most 22-year-olds burn their paychecks on depreciating gadgets. But smart techies build guaranteed wealth! Take a look at this exclusive product: The Apex Guaranteed Wealth & Life Shield! 100% tax-free under Section 80C and 10(10D)!"
"Here is our exclusive structure: You deposit just ₹1 Lakh per year for 10 years. In return, you get a ₹10 Lakhs life cover completely FREE, and at Year 20, you collect a guaranteed ₹20 Lakhs tax-free cheque! You literally DOUBLE your money with ZERO market risk!"
"Wait... ₹20 Lakhs guaranteed? That’s literally double of my ₹10 Lakhs total deposit! Plus my family gets ₹10 Lakhs if anything ever happens to me? That sounds like the absolute perfect all-in-one financial plan!"
"Our branch quota only has two allocation slots remaining for this exclusive tranche, Rahul sir. Just put your initial here on page 4, 8, and 12, and I’ll set up your automated ECS debit today. Lock in your financial destiny before the IRDAI interest rates reset tomorrow!"
"Uh... Rajesh ji, my team lead just pinged me for our daily engineering sprint. Let me take this policy brochure and review the terms and conditions tonight. I'll drop by tomorrow after standup!"
"Priya! Sharmaji! Look at this financial goldmine! The Apex Bank RM offered me an elite guaranteed plan: Pay ₹1 Lakh/yr for 10 years, get ₹10 Lakhs life cover, and collect a guaranteed ₹20 Lakhs at Year 20! I’m going back to sign tomorrow!"
"Apex Guaranteed Wealth... Rahul, this isn't an investment; it’s an old-school Endowment / ULIP trap! Did Rajesh happen to show you the annualized Internal Rate of Return (IRR) or the charge deduction schedules?"
"Never judge an investment by the gross rupee number 20 years away. Let's feed the exact cash flows into the standard financial formula: The Internal Rate of Return (IRR). Ten annual cash outflows of ₹1 Lakh, a ten-year wait, then a ₹20 Lakh inflow."
"Look at the screen, Rahul: 4.83%! Not 12%, not 8%, but barely 4.8%! That 'doubling your money' soundbite over a 20-year span translates to an annualized return LOWER than an ordinary 1-year bank Fixed Deposit!"
"Rahul beta, Indian retail inflation (CPI) averages 5.5% to 6.0% every year. At 4.8% return, your money is literally melting! In 20 years, that 'guaranteed' ₹20 Lakhs will have the purchasing power of barely ₹6.2 Lakhs in today's money. It is guaranteed wealth destruction!"
"Where does your money go? High front-loaded charges! In Years 1 to 3, 10% to 25% of your ₹1 Lakh premium is sliced off to pay the bank's sales commission, policy admin fees, and mortality charges. Only the small leftover crumb is actually invested!"
"And look at the life cover—₹10 Lakhs! Rahul, if an untimely tragedy strikes, your family receives ₹10 Lakhs. In a city like Bangalore, ₹10 Lakhs barely covers 14 months of rent, food, and basic utilities! Calling this 'life protection' is a dangerous illusion!"
"The Golden Commandment of Personal Finance: NEVER mix insurance with investment! Insurance is a risk-transfer shield designed to absorb catastrophic downside. Investment is an asset-accumulation engine designed to capture upside. Mixing them sabotages both!"
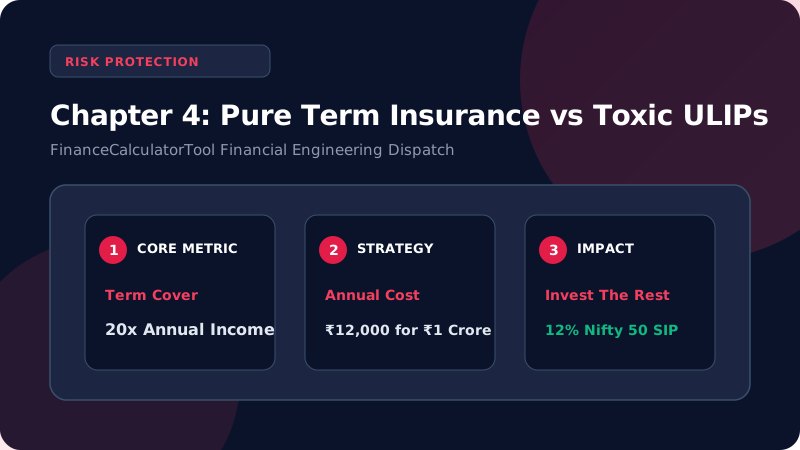
"Pillar 1: Pure Term Life Insurance! At age 22, because you are young, non-smoker, and healthy, a ₹1 Crore Pure Term policy costs just ₹9,000 per year—that’s only ₹750 a month, less than a couple of weekend Swiggy orders!"
"Look at your budget, Rahul: You were ready to hand Rajesh ₹1,00,000 every single year. Pay ₹9,000 for your unbreakable ₹1 Crore safety shield. That leaves a massive ₹91,000 every year—or ₹7,583 per month—to invest directly in pure compounding!"
"Pillar 2: Direct Nifty 50 Index SIP! Invest that ₹91,000/year into India’s top 50 blue-chip companies with an ultra-low 0.1% expense ratio. At a historical 12% CAGR, in 20 years your investment compounds to a staggering ₹73.4 Lakhs!"
Choose Your Move
Rahul has â¹50,000/year to deploy. Which path builds real generational wealth?
Buy the 10-year ULIP / Endowment plan (5% return, â¹5L cover)
â¹1 Crore Term Plan (â¹8k) + Direct Index SIP (â¹42k/yr)
Act 3: The Winning Separation Formula
"Step 1: Buy a Pure Term Life Insurance plan for â¹1 Crore cover (costs just â¹8,000/year at age 22). Step 2: Invest the remaining â¹42,000/year (â¹3,500/mo) in a Nifty 50 Direct Index Fund at 12% CAGR. In 15 years, your index fund corpus is â¹18.2 Lakhs, AND you have â¹1 Crore life protection!"
Executive Checklist
1. Take a Pure Term Plan of at least 15â20x Annual Income
For a â¹12 LPA salary, take a â¹1.5â2 Crore term policy up to age 60.
2. Surrender or Stop Toxic Endowment Policies
Calculate the surrender value and reinvest proceeds into low-cost index funds.
Calculate Your Human Life Value (HLV) & Term Cover Needs
Enter your age and income to see the exact recommended term insurance coverage amount.
Knowledge Challenge Quiz
Test your retention of this chapter's critical financial lessons