Part 1: The LinkedIn Post & The First Payday Shock
Panels 1 to 18 • Bangalore Tech Corridor Investigation
"Behold the beast! Top trim, panoramic sunroof, ventilated leatherette seats, 10-inch touchscreen! Level up, boys—this is how a real tech lead arrives!"
"Rahul, my man! Zero down payment! The dealership finance guy hooked me up with an 84-month, 7-year loan! The EMI is just ₹28,000 a month—practically pocket change from our salary!"
"₹28,000 EMI? Wait... our take-home is ₹76,400. If Tarun can do it, could I? Imagine driving this home to Mysore... the respect, the pride!"
"Good morning, boys. Nice paint job, Tarun. Did I just hear you say 'Zero Down Payment' and '7-Year Loan' in the same breath?"
"Tarun, you didn't just buy a car. You signed a 7-year financial hostage contract. Let's head up to the cafeteria before you drive yourself into personal bankruptcy."
"Most 22-year-olds fall for the 'EMI Illusion'. They think owning a car only costs the monthly EMI. In reality, an automobile is an iceberg—the EMI is just the tiny tip above the water!"
"Meet Total Cost of Ownership—TCO. When you sign for a car, you aren't just paying the bank. You are legally contracted to pay petrol companies, insurance cartels, service garages, and tech park parking operators!"
"Bangalore bumper-to-bumper traffic gives 8 km per liter. That's ₹6,500 in petrol! Bumper-to-bumper Zero-Dep insurance renewal is ₹48,000 a year—that's ₹4,000 a month! Service and tyres add ₹3,000! Tech park parking and tolls: ₹2,500!"
"Total monthly vehicle drain: ₹44,000 every single month! Not ₹28,000. Every 30 days, ₹44,000 leaves your pocket just to keep that red metal box on the road!"
"F-forty-four thousand?! Wait... my monthly take-home after PF and taxes is ₹76,400! If ₹44,000 goes to the car... what do I even have left?!"
"₹44,000 out of ₹76,400 is FIFTY-SEVEN POINT SIX PERCENT! Tarun, you are trading 58% of your working hours every month just to drive a car that sits parked 90% of the day!"
"And don't forget Bangalore reality, beta! Your 1BHK rent in Bellandur is ₹22,000. Food and utilities cost ₹12,000. ₹44k + ₹22k + ₹12k = ₹78,000! You are ₹1,600 in the NEGATIVE every month without investing a single rupee!"
"In our culture, uncles say: 'Car is an asset, beta! It builds status!' But in accounting, an asset puts money INTO your pocket. A car only sucks cash OUT. A car is a rapidly depreciating consumer appliance!"
"The second the showroom wheels touch the road, 15% is gone. By the end of Year 1, 25% of your money has vanished! By Year 4, it has lost half its value. In Year 7, your ₹16 Lakh pride is worth barely ₹5.4 Lakhs!"
"Here is the trap of an 84-month loan: Negative Equity! In the first 3 years, your EMI mostly pays bank interest. In Year 3, you owe the bank ₹11.15 Lakhs, but the market only gives you ₹8.67 Lakhs! You are ₹2.48 Lakhs UNDERWATER!"
"Now let's look at the real tragedy: Opportunity Cost! Money spent on petrol and bank interest cannot compound. What happens if Tarun redirects that ₹44,000 a month into a low-cost Nifty 50 Direct Index SIP over those exact same 7 years?"
Choose Your Move
Rahul is tempted to buy a â¹16 Lakh compact SUV on an 84-month zero-downpayment loan like Tarun. How should he plan his Bangalore daily commute?
Book â¹16L SUV on 7-Year Loan (â¹44,000/mo Total Burn)
Certified Used Hatchback / Metro + â¹30,000/mo Index SIP
Act 3: Sharmaji Explains Negative Equity & The â¹52L Opportunity Cost
"Investing that â¹44,000 monthly difference into a Nifty 50 index fund at 12% CAGR over 7 years grows to â¹58.07 Lakhs. The car ends up worth â¹4.5 Lakhs. That is a â¹53 Lakh wealth gap!"
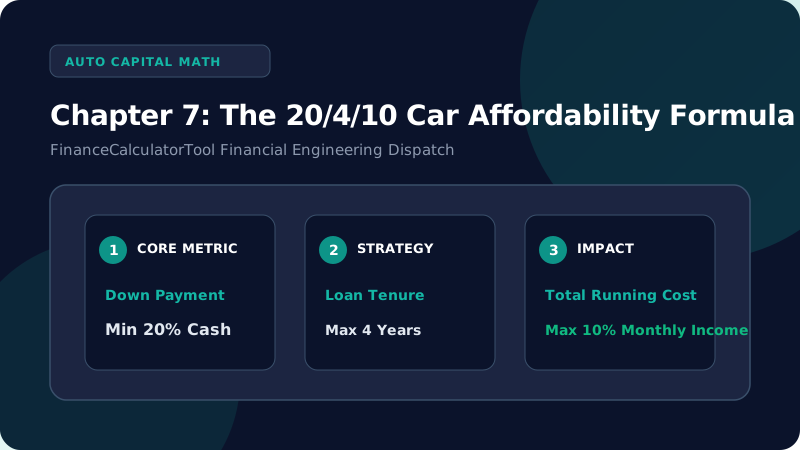
Act 4: The 20/4/10 Rule for Sovereign Mobility
"Put down at least 20% in cash. Finance for maximum 4 years (48 months). And total monthly burn (EMI + fuel + insurance + service) must stay strictly under 10% of your take-home pay!"
Executive Checklist
1. Calculate Total Cost of Ownership (TCO), Not Just EMI
Add monthly EMI + â¹6,000 fuel + â¹3,500 insurance + â¹2,000 service reserve to know your real drain.
2. Enforce the 20/4/10 Boundary Before Stepping into a Dealership
Save 20% cash down payment first. Never accept 7-year loans or let total vehicle costs exceed 10% of take-home.
3. Channel the Car Savings Gap into a Nifty 50 SIP
Investing â¹30,000/mo instead of funding depreciation builds â¹27.5+ Lakhs of liquid net worth in 5 years.
Exercise the Car Loan EMI & On-Road Price Calculator
Test different down payment amounts, tenures, and interest rates to verify the 20/4/10 rule.
Knowledge Challenge Quiz
Test your retention of this chapter's critical financial lessons