Part 1: One Year Later: Wealth Creation & The ₹1.8 Cr Commission Trap
Panels 1 to 18 • Bangalore Tech Corridor Investigation
"One year complete! Emergency fund locked in Auto-Sweep and Liquid Funds, pure term shield active, credit cards paid in full. Defense is 100% airtight!"
"Wait a second... I have ₹95,000 surplus idling in my savings account earning 3% interest while Bangalore inflation is over 6%! My hard-earned money is slowly bleeding value!"
"Rahul, you're 22! Don't stress about investing ₹10k or ₹15k a month—it’s pocket change! Wait until your 30s when you're a manager like me. I invest ₹25,000 a month! That's real capital volume!"
"Amit, that is mathematically the worst advice you could ever give a 22-year-old! A 22-year-old putting in ₹10,000 a month will retire with crores MORE wealth than a 32-year-old investing ₹25,000!"
"And look at my setup! My bank RM handles my mutual fund SIPs personally right at my desk. Zero platform charges, zero advisory fees. Free VIP service!"
"Amit... in finance, if you don't know who is paying for the service, YOU are the product! Look at those two words: 'REGULAR PLAN'. Your 'free' RM is taking a silent 1.5% commission cut every single year!"
"Did I hear someone mention 'Regular Mutual Funds'? In 25 years of running payroll seminars, this single 1.5% leak has stolen more employee retirement fortunes than market crashes ever did!"
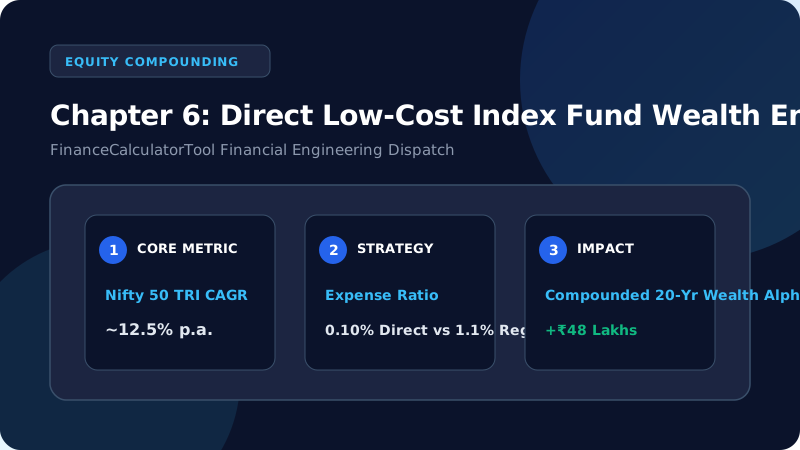
"Every mutual fund in India exists in two versions. In 'Direct', you buy straight from the fund house: Total Expense Ratio (TER) is just 0.08%. In 'Regular', the broker adds a 1.5% annual kickback for themselves!"
"Come on Priya, it's just 1.5%! If the Nifty gives 12%, getting 10.5% isn't that big a deal. Isn't 1.5% just a modest tip for my relationship manager?"
"Amit! That 1.5% is NOT charged on your profit! It is shaved off your ENTIRE PORTFOLIO every single trading day! When your portfolio reaches ₹1 Crore, the bank takes ₹1,50,000 that year—even if the market falls 20% and you lose money!"
"Look at the terminal math: At ₹15,000 a month for 30 years, Direct Plan gives you ₹5.29 Crores. Regular Plan gives you only ₹3.81 Crores! That 'tiny 1.5% tip' stole nearly ONE AND A HALF CRORES of your life savings!"
"One point five CRORES?! Over my career, I was going to hand my bank relationship manager a luxury 3BHK flat in Whitefield for doing 10 minutes of paperwork?!"
"In 2013, SEBI stepped in and forced all mutual funds to launch 'Direct Plans' with separate, higher NAVs and zero distributor commissions. All you have to do is select the word 'DIRECT - GROWTH'!"
"Behold the Compounding Pyramid! In your first 10 years, it feels like regular saving. But look at Tier 2 and Tier 3: in the third decade alone, your corpus explodes by nearly FOUR CRORES!"
"Wait... from age 42 to 52, I only contribute another ₹18 Lakhs from my salary, but my wealth leaps from ₹1.49 Crores to ₹5.29 Crores?! The interest makes more than twice my entire 30-year salary savings!"
"Look at the formula! Capital 'P' is multiplied linearly, but time 'n' sits up in the exponent! When you increase time, wealth multiplies exponentially. That is why age 22 is your ultimate financial superpower!"
"Look at the brutal cost of procrastination! If you delay your ₹15,000 SIP by just 5 years—starting at 27 instead of 22—you only save ₹9 Lakhs in cash, but you lose ₹2.44 to ₹2.7 CRORES at age 52! Each year of delay costs ₹50 Lakhs!"
Choose Your Move
Which mutual fund plan should Rahul select for his monthly â¹10,000 Nifty 50 Index SIP?
Invest via bank relationship manager in "Regular Plan"
Invest in "Direct Plan - Growth" via AMC or zero-fee platform
Act 3: The Silent 1.5% Broker Commission Leak
"Rahul, switch to DIRECT Plan immediately! In a Regular Plan, the bank/broker skims 1.2% to 1.5% distributor commission every single year from your entire corpus! Over 30 years, that tiny 1.5% commission will steal â¹1.5 CRORES of your personal wealth!"
Executive Checklist
1. Open a Direct Mutual Fund Account (Zero Brokerage)
Ensure all mutual fund folios specify "Direct - Growth". Avoid third-party regular distributors.
2. Start with a Low-Cost Nifty 50 Index Fund
Expense ratio should be under 0.2%. Index funds track Indiaâs top 50 companies automatically.
3. Enable Step-Up SIP (Increase 10% Every Year)
When your salary increases with annual appraisals, top up your monthly SIP automatically.
See the Delay in SIP Opportunity Cost on the Live Calculator
Calculate how delaying your monthly SIP by just 1 to 5 years destroys crores in compounding wealth.
Knowledge Challenge Quiz
Test your retention of this chapter's critical financial lessons