Part 1: The HR Tax Deadline Email & The 80C Panic
Panels 1 to 18 • Bangalore Tech Corridor Investigation
"₹28,400 deducted per month?! That’s over a third of my take-home salary gone! If they cut that from my January paycheck, I won't even have enough for my flat rent and groceries!"
"Rahul! Tell me you saw the HR email! Five days left! Did you invest your ₹1.5 Lakhs in 80C tax-savers yet, or are you going to let the tax department wipe out your entire winter salary?!"
"Take these! You must lock ₹1,50,000 into an ELSS mutual fund immediately! Plus ₹25,000 in health insurance and ₹50,000 in NPS! That’s how my dad did it, that’s how I've done it for 8 years!"
"I only have ₹1.42 Lakhs in total savings! If I lock it into a 3-year ELSS fund today, I have ZERO liquid cash for medical emergencies or rent! Is adult life just a choice between tax penalties and going broke?!"
"Listen Rahul, if you're short on cash, take a pre-approved quick personal loan on your banking app or swipe your credit card for an ELSS lump-sum! Anything is better than letting HR cut taxes!"
"Vikram, take a breath. Put those brochures on the table. Rahul, do NOT swipe your credit card, and do NOT lock your emergency fund in a 3-year lock-in. Sit down, both of you."
"Priya, it’s ₹1,50,000 in deductions! If Rahul doesn't claim 80C, he's basically gifting his hard-earned money to the government! It’s the golden rule of salaried life!"
"Namaste team! Every January for twenty-five years, I see young engineers run around like the building is on fire over Section 80C. What is the panic about today?"
"Vikram is stuck in 2019. Sharmaji, tell Rahul: under the Finance Act 2024, what is the default tax regime for salaried employees in India, and what did it do to the Standard Deduction?"
"Wait... the New Tax Regime? Vikram said that’s a trap because you can't claim 80C or rent! Is there actually a way to pay zero or low tax without locking away ₹1.5 Lakhs?!"
"Let's put the emotion aside and run the cold, hard numbers. Rahul's Fixed Base CTC is ₹10.5 Lakhs. Let’s see what happens under both regimes, starting with the biggest gift of Budget 2024!"
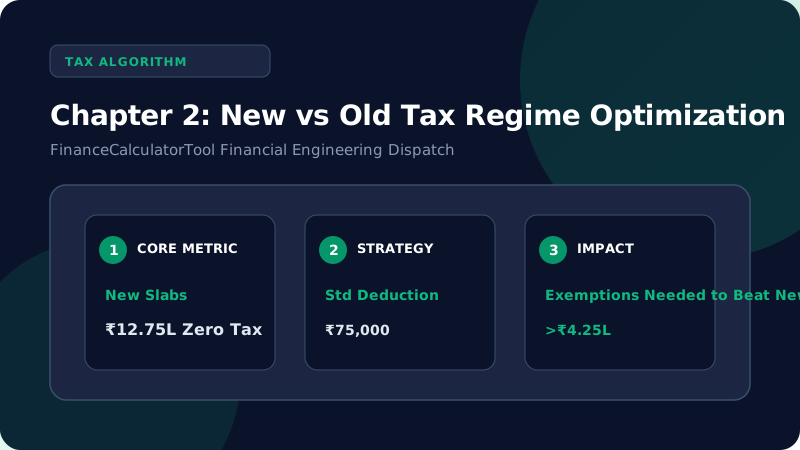
"Pillar 1: Standard Deduction! Under the Old Regime, it’s capped at ₹50,000. But under the New Regime, Budget 2024 boosted it to ₹75,000! You get this ₹75,000 tax deduction automatically—no receipts, no proofs, no lock-in!"
"Pillar 2: Section 80CCD(2) and Employer EPF! Nexa Tech contributes 12% of your Basic directly into your EPF (₹72,000/year). That ₹72,000 is completely tax-exempt under BOTH regimes! It is already deducted from your taxable gross!"
"Look at these slabs! 0 to 3L is ZERO. 3 to 7L is just 5%! And if your taxable income is up to ₹7 Lakhs (that’s ₹7.75 Lakhs gross with standard deduction), Section 87A makes your tax literally ₹0!"
Choose Your Move
Rahul earns â¹12 LPA. Should he lock â¹1.5 Lakhs in an insurance policy to claim 80C under the Old Regime, or choose the New Regime?
Choose Old Regime & lock â¹1.5L in low-yield 80C policies
Choose New Regime with â¹0 Tax & Zero Paperwork
Executive Checklist
1. Select "New Tax Regime" on Company HR Portal
Unless your total annual deductions (HRA + 80C + 80D + Home Loan Interest) exceed â¹4.25 Lakhs, New Regime wins hands down.
2. Avoid High-Commission 80C Insurance Products
Say no to ULIPs and endowment plans pushed by bank agents during February and March.
Compare Old vs. New Regime on the Live Calculator
See side-by-side tax calculations and find your exact breakeven deduction point.
Knowledge Challenge Quiz
Test your retention of this chapter's critical financial lessons