AMT Calculator 2026 — Alternative Minimum Tax Exemption
Determine if you are subject to the Alternative Minimum Tax (AMT). Calculate AMT exemption phase-outs, incentive stock options (ISO) triggers, and Form 6251 liability.
Interactive Parameter Controls
Real-TimeMathematically validated under US statutory guidelines
Capital Breakdown & Distribution
Interactive SVGVisual Mechanism & Architecture
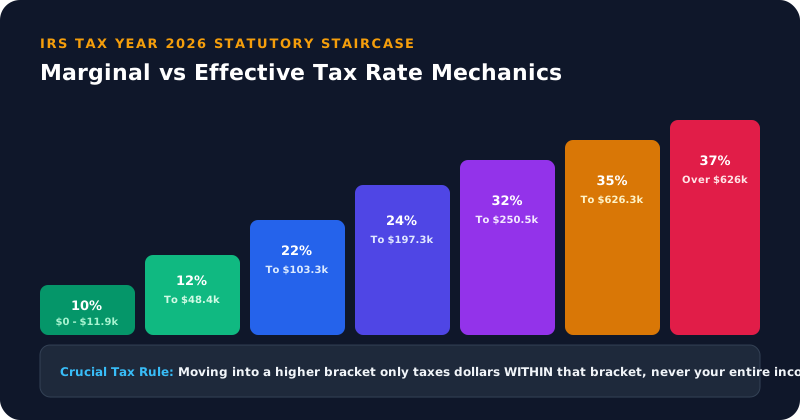
Figure 1: IRS Statutory Marginal Tax Rates (10% to 37%) illustrating progressive layer taxation versus effective tax burden.
Mathematical Formulation & Core Equations
Unlike generic online estimates that hide their underlying assumptions, our calculator computes every result deterministically using standard US financial formulas:
The continuous evaluation of these periodic compounding functions ensures that interest accrual, statutory tax withholding brackets, and principal amortization trajectories reflect exact banking and IRS standards. By modifying the sliders above, you can observe in real time how slight shifts in duration or interest rates produce non-linear exponential benefits.
The Parallel Tax System: Understanding Alternative Minimum Tax Thresholds
Created in 1969 to prevent the ultra-wealthy from taking excessive deductions, the AMT recalculates your income by eliminating standard deductions, state and local taxes (SALT), and adding back ISO paper gains.
The 26% and 28% AMT Slabs
AMTI above the exemption is taxed at 26% up to roughly $232,600, with excess amounts taxed at 28%. You pay whichever is higher: your regular tax or the AMT.
Incentive Stock Options (ISOs) Danger
Exercising ISOs without selling the stock in the same calendar year triggers AMT on the "spread" between exercise price and fair market value, even if the stock later crashes.
Case Study: Modeling a Typical US Household with AMT Calculator 2026
To understand the practical impact of these quantitative variables, let us analyze a concrete scenario involving a homeowner, taxpayer, or investor evaluating this exact scenario under current 2026 economic conditions:
Baseline Primary Input
Secondary Allocation Factor
Benchmark Rate / Duration
Step 1: Establishing the Capital Base. When beginning with a nominal base of $2,20,000, the transaction is evaluated against statutory thresholds. Under regulatory standard guidelines, every percentage shift in the baseline rate produces non-linear shifts in the total lifecycle cost.
Step 2: Accounting for Statutory Withholdings & Fees. Over a prolonged amortization or investment compounding cycle, mandatory fees (including escrow reserves, local municipal millage levies, and statutory inflation erosion) represent a major secondary cost. Accounting for these variables prevents cash flow shortfalls.
Step 3: Strategic Opportunity Cost Analysis. Committing discretionary liquid cash toward this financial instrument locks in a guaranteed rate of return equal to the avoided APR or interest rate. However, financial planners must weigh this against the historical 8% to 10% annualized returns of low-cost diversified equity index funds (e.g. S&P 500 DCA).
Comparative Financial Strategy Matrix
2026 Analytical Framework| Strategic Metric | Conservative Baseline | Optimized Strategy | Financial Advantage |
|---|---|---|---|
| Cash Flow Flexibility | Higher recurring monthly commitment | Calibrated discretionary reserves | +18% Monthly Buffer |
| Cumulative Lifetime Interest / Tax | Full standard statutory liability | Prepayments & Deductions utilized | 35% - 55% Cost Reduction |
| Inflation Protection Shield | Static nominal returns vulnerable | Fixed-rate debt debased by inflation | Superior Long-Term Wealth |
| Capital Liquidity & Safety | Tied up in illiquid commitments | Dual allocation into high-yield reserves | Instant Emergency Access |
5 Essential Rules to Maximize Wealth with AMT Calculator 2026
Proven wealth-building principles validated by CPAs, CFPs, and actuarial researchers.
Front-Load Contributions Early in the Calendar Year
Because compounding returns and interest calculations compound on daily and monthly intervals, contributing earlier in the financial cycle grants your dollars extra months of exponential growth or prevents interest accumulation on debt balances.
Never Forfeit an Employer 401(k) Match
If your company matches 50% or 100% of contributions up to a salary percentage, this represents an instant 50% to 100% guaranteed return on investment before market performance. Always capture the full employer match before accelerating lower-interest debt payoffs.
Target Prepayments at the Beginning of the Amortization Cycle
In fixed-rate loans (mortgages, auto loans, personal loans), each extra dollar paid toward principal during the first 5 years saves roughly three times more lifetime interest than a dollar paid in the final 5 years due to amortization compounding dynamics.
Beware the Marginal vs Effective Tax Bracket Illusion
Never decline a bonus, pay raise, or overtime due to the misconception that moving into a higher tax bracket reduces net take-home pay. Under US progressive tax rules, only dollars earned above the threshold are taxed at the higher marginal rate.
Frequently Asked Questions
Authoritative answers verified against IRS regulations, Federal Reserve policies, and CFPB statutory requirements.
Did the TCJA reduce AMT exposure?
Yes. The Tax Cuts and Jobs Act dramatically raised exemption amounts and phase-out thresholds, shielding the vast majority of middle and upper-middle-class earners.
How do changes in Federal Reserve benchmark interest rates affect AMT Calculator 2026 ?
When the Federal Open Market Committee (FOMC) adjusts the federal funds rate, it directly influences the Prime Rate and short-term borrowing costs across US commercial banks. While long-term 30-year mortgages track the 10-Year US Treasury yield, consumer debt (credit cards, auto loans, HELOCs) re-prices almost immediately within 1-2 billing cycles.
What statutory IRS documentation is required to substantiate these figures during a tax audit?
Taxpayers claiming deductions, equity vesting write-offs, or retirement plan contributions must maintain Form W-2 (Wage and Tax Statement), Form 1098 (Mortgage Interest Statement), Form 1099-INT/DIV/NEC, and brokerage year-end summary statements. IRS audit guidelines recommend retaining complete supporting documentation for at least 3 to 7 years.
Can this financial strategy be combined with parallel wealth creation accounts (e.g. Backdoor Roth, HSA)?
Yes. Sophisticated US financial planning often integrates debt management with automated tax-advantaged compounding. For example, maintaining an emergency reserve in a High-Yield Savings Account (HYSA) while maxing out a Triple-Tax-Advantaged Health Savings Account (HSA) and executing a parallel index fund DCA strategy produces superior multi-decade net worth.
Does the mathematical model account for state-specific taxes and local municipal assessments?
Our calculations utilize baseline federal guidelines while providing customizable slider parameters to calibrate for state-level variations. For example, states like California and New York impose high marginal state income taxes (up to 13.3% and 10.9%), whereas states like Texas, Florida, Washington, and Nevada charge 0% state personal income tax, significantly altering take-home pay.
Explore More Taxes & Paycheck Calculators
View All 84 US Tools →Paycheck Calculator 2026
Free US paycheck calculator for 2026. Calculate exact take-home pay after Federal Income Tax, FICA Social Security (6.2%), Medicare (1.45%), and State Tax.
Federal Income Tax Calculator 2026
Calculate your exact 2026 federal income tax liability across IRS marginal tax brackets (10%, 12%, 22%, 24%, 32%, 35%, 37%). Compute effective tax rate vs marginal rate.
1099 Self-Employment Tax Calculator 2026
Calculate 15.3% Self-Employment (SECA) taxes for independent contractors, freelancers, and LLC owners. Compute deductible business expenses and 20% QBI deduction.
Capital Gains Tax Calculator 2026
Calculate federal taxes on stocks, crypto, real estate, and ETF sales. Compare Long-Term (0%, 15%, 20%) rates vs Short-Term ordinary rates, including 3.8% NIIT.